Your Local Mortgage Lender
Located in Beverly Hills, California
Personalized Mortgage Experience
Mitchell Milat offers personalized service and loan options you'll love. We shop multiple lenders to find the best rate and product for you, getting you into your dream home faster.
With wholesale interest rates and cutting-edge technology, we make the mortgage process seamless. Trust the experts who focus solely on mortgages. Support your local community and experience elite client service.
Let us help you achieve your homeownership dreams!
The Home Loan Process
Mortgage Pre-Approval
Get pre-approved from one of our Loan Officers to see how much you can afford.
House Shopping
Work with a trusted Real Estate Agent to find a home you would like to move into.
Loan Application
Complete your home loan application to get the lending process started.
Don't take my word for it
Mortgage Programs
Experience the best mortgage experience located in Beverly Hills, California.
Home Loan Options
Our experienced mortgage advisors will walk you through the best mortgage loan program that will fit your specific scenario.
Conventional Home Loans.
FHA Home Loans.
USDA Home Loans.
VA Home Loans.
Frequently Asked Questions
How often can I refinance my mortgage?
There is no limit to the number of times you can refinance. However, you must qualify every time you apply and there will be costs associated with closing the loan each time.
Can I buy a home if I do not have money for a down payment?
Yes! There are a number of bond programs that offer low or no down payment financing options.
How do I know which mortgage is right for me?
The key to choosing the right mortgage is to understand the range of options and features available to you, as well as your budget, circumstances, and goals. Our licensed mortgage professionals are here to help you navigate that process. The more you know, the more comfortable and confident you will be choosing the best option for you and your family.
How long will the loan process take?
The Truth in Lending Act (TILA) does not permit a lender to close a loan until at least seven (7) business days have passed from the date your application was received. A typical home loan takes 30 days, as a number of third-party services such as appraisals, title work, and credit are required in conjunction with the mortgage process. Once you familiarize your Loan Officer with the details of your specific loan scenario, they will be able to provide you with a more specific timeline.
Will I qualify for a home loan?
The only way to find out is to speak with a qualified mortgage professional. Our Loan Officers have helped numerous clients who didn’t know if they could qualify to become home owners. We take the time to understand your financial situation and long-term financial goals, and then match you with the loan program that best fits your needs. Your approval for a loan may also largely depend on the price of the home you are financing. Getting pre-qualified prior to beginning your home search can give you an idea of what you may be able to afford.
Why do people refinance their mortgages?
Homeowners typically refinance to save money, either by obtaining a lower interest rate or by reducing the term of their loan. Refinancing is also a way to convert an adjustable loan to a fixed loan or to consolidate debts.
How much money will I have to pay upfront to buy a home?
This question does not have a simple, one-size-fits-all answer. The exact amount will depend on the price of the home you buy as well the type of mortgage financing you choose. Depending on your loan program, your down payment could be as much as 20% of the home’s price or as little as 3%, while some loans require no down payment at all.
Can I get a mortgage after bankruptcy?
You may still qualify for a home loan even if you have experienced a bankruptcy. The best way to find out if you qualify is to talk with a Loan Officer to discuss your options. Be sure to bring all paperwork regarding your bankruptcy so your Loan Officer can find the program that best fits your situation.
Should I lock my interest rate now, or wait until we are closer to our closing?
Interest rates fluctuate all day, every day. If an interest rate is good, it may be in your best interest to lock now. If you wait, you run the risk of an increase in rates later. If you are concerned that rates may go down after you lock, contact your Loan Officer to discuss your options. Some programs allow you to lock for an extended period and choose to lower your rate should a better one become available.
Most Recent Blog Updates
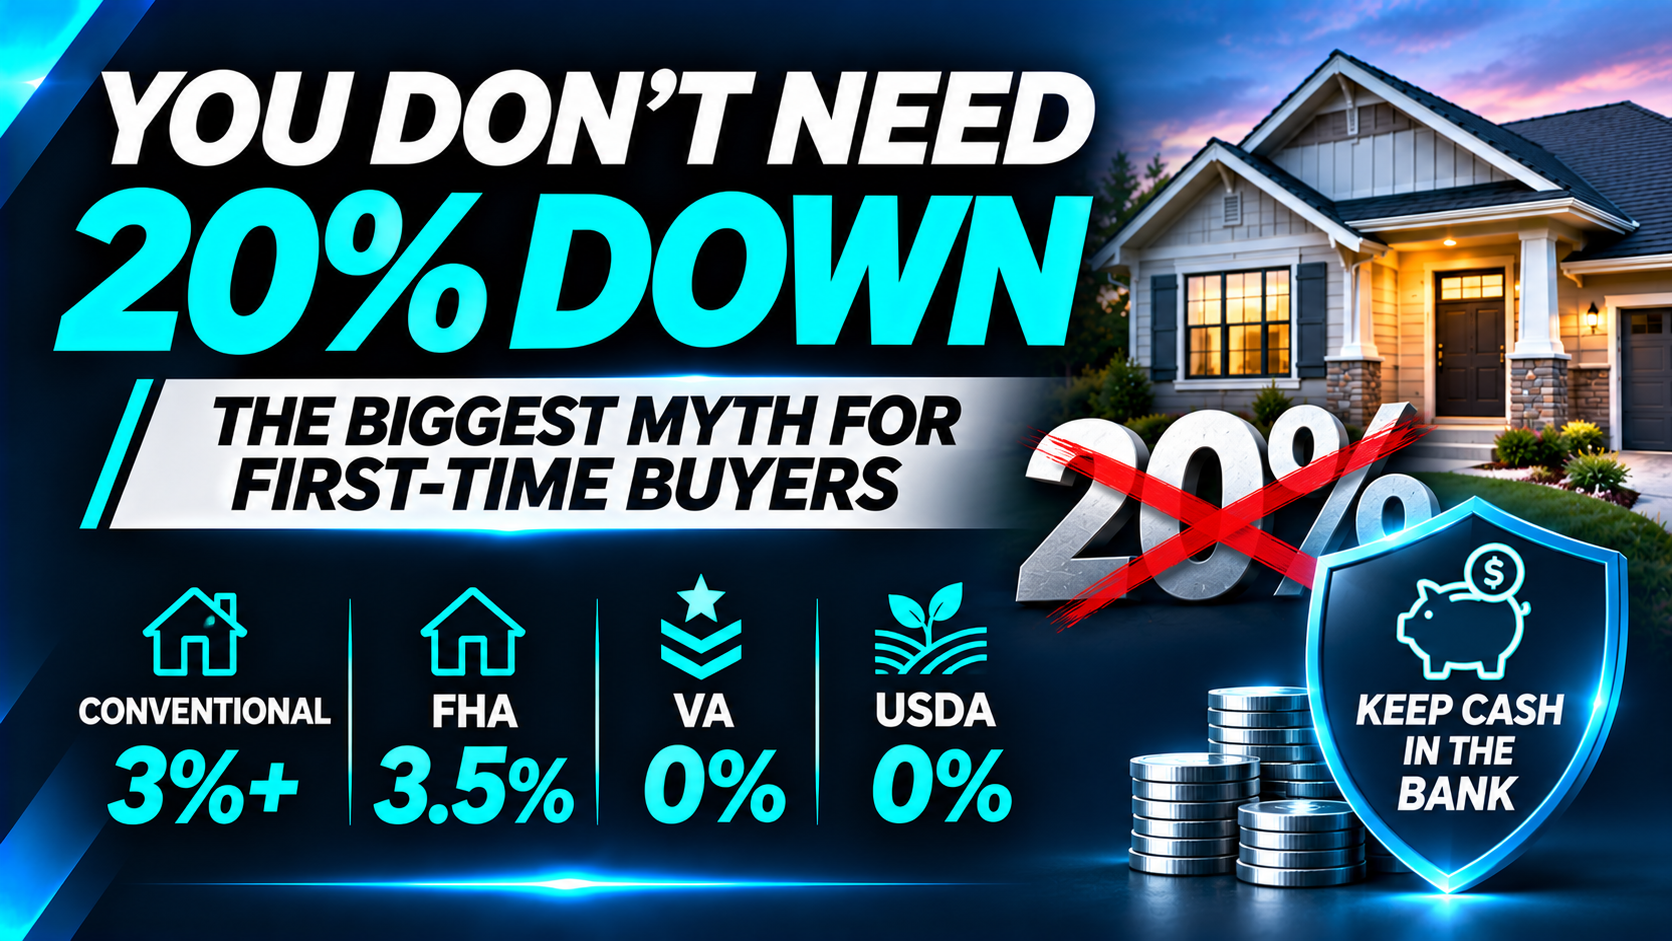
Most Buyers Never Put 20% Down: Mitch Milat Busts the Biggest First-Time Buyer Myth
The Biggest Myth First-Time Buyers Believe
Mitch Milat says the biggest myth he hears from first-time buyers is that you have to put 20% down to buy a home. Most buyers never do. According to Mitch, the typical first-time buyer puts down around 8%, and plenty of good loans require far less. Understanding this can help you start your home search sooner and with more confidence.
Low Down Payment Loan Options
Many conventional loans allow as little as 3% down. FHA loans allow as little as 3.5% down. VA and USDA loans can offer 0% down for borrowers who qualify. Each program has its own requirements, including credit standards, income or location limits, and property guidelines, so the best fit depends on your situation. Terms and eligibility vary by lender and borrower.
What About Mortgage Insurance?
Putting less than 20% down usually means paying mortgage insurance for a while. On a conventional loan, however, private mortgage insurance can fall off once you build enough equity, whether through paying down the balance or through home value growth. Mortgage insurance on other loan types, such as FHA, follows different rules, so it is worth asking how it works on the specific program you are considering.
The Cost of Waiting Years to Save
Mitch points out that waiting years to save 20% can cost more than the insurance ever would. While you save, home prices and rents may keep rising, and you miss out on the chance to build equity as an owner. Market conditions differ by area and nothing is guaranteed, so it is wise to compare your own numbers rather than assume waiting is the safer path.
Ask a Smarter Question
Rather than asking how to reach 20%, Mitch suggests asking how much you can put down while still keeping a healthy emergency fund. Holding back cash for repairs, moving costs, and unexpected expenses can matter just as much as the down payment itself. Balancing the two helps you buy with a cushion instead of stretching every dollar.
Let’s Look at Your Options Together
If you are thinking about buying, Mitch Milat can walk through your options with you and show what different down payment amounts could mean for your monthly payment and your savings. Reach out to start the conversation.
Sources
ConsumerFinancialProtectionBureau.gov
FreddieMac.com
Fanniemae.com
HUD.gov
NAR.realtor

Mortgage Calculator
See your total mortgage payments using the tool below.
| Year | Interest | Principal | Balance |
|---|

Social Media Links
YouTube
